Valuing a business means putting a price on a combination of assets, financial flows and prospects, all of which can be viewed differently depending on the objective. Whether the transaction involves a sale, a family succession or an investor coming on board, the business valuation methods used do not produce a single figure. Instead, they establish a range whose breadth depends on the assumptions made and the quality of the available data.
Valuation and sale price: why the gap persists
Sellers often base their valuation on what they believe they have invested in the business in terms of time, capital and business development. Buyers, on the other hand, focus on what the business can earn for them after the acquisition. These two perspectives are present in every transaction, and it is precisely the tension between them that determines the final price.
An expert’s calculated value remains a technical estimate. It does not account for the balance of power between the parties, the urgency of the sale or the scarcity of the business in its market. A buyer in a hurry to secure a profitable business may be willing to pay above the lower end of the range, while a seller facing retirement may accept a discount.
Several business valuation methods can help structure these negotiations, but none replaces the final agreement between buyer and seller.
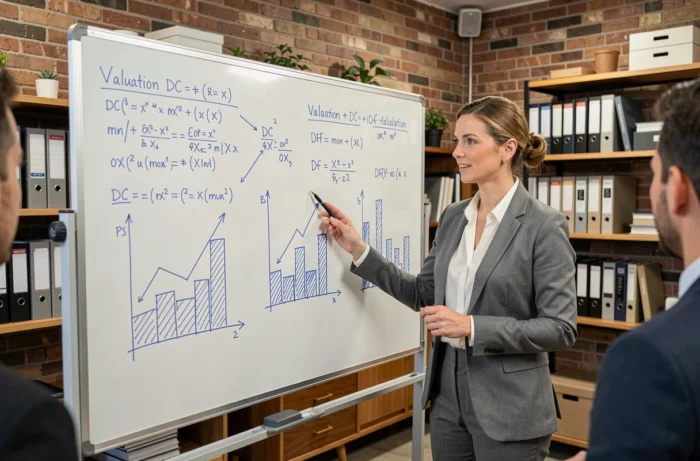
Asset-based approach: what the business actually owns
Asset-based valuation starts with the balance sheet. It adds up the assets (property, equipment, inventory and cash) and subtracts liabilities to determine net assets. The result is a snapshot of what the business is “worth” at a given point in time, based solely on what it owns.
This method is suitable for businesses whose value is based on tangible assets, such as property companies, industrial businesses with significant machinery or trading companies with substantial inventory. However, it has its limitations when the business’s future profitability far exceeds the value of its accumulated assets.
Net book value does not always reflect economic reality
Balance sheet values follow depreciation rules that do not necessarily correspond to the market value of assets. A property acquired twenty years ago may be listed on the balance sheet at a fraction of its current price. Conversely, computer equipment depreciated over three years may still be functional but recorded at zero.
To correct these distortions, the adjusted net asset value is recalculated by revaluing each item at its market value. This adjustment is necessary for the asset-based approach to produce a figure that can be used in negotiations.
Earnings-based method: valuing cash flows rather than assets
The earnings-based approach focuses on what the business generates, not what it owns. It involves discounting future financial flows (profits, EBITDA or free cash flow) to determine their present value.
The principle is simple: a dollar received in three years is worth less than a dollar received today. The discount rate takes into account the cost of capital and a risk premium based on the sector, the size of the business and the reliability of its forecasts. The higher the perceived risk, the higher the rate and the lower the valuation.
Financial forecasts: the sensitive link
The reliability of this method depends entirely on the quality of the projections. An optimistic business plan will inflate the valuation, while conservative assumptions will bring it down. IPEV guidelines emphasize that rates and forecasts should reflect market participant assumptions, not just those of the owner.
In practice, adjustments cover several areas:
- The owner’s compensation, which is often above or below market rates, distorting the actual net profit
- Exceptional expenses and income that will not recur after the sale and should therefore be excluded
- Provisions set aside as a matter of accounting prudence, which may obscure the business’s actual earnings capacity
Without these adjustments, reported profitability can differ significantly from actual economic profitability.
Comparable company valuation: when the market sets the benchmark
The comparable company method involves comparing the business with recent transactions involving similar companies in terms of size, sector and geographic area. Multiples (revenue, EBITDA or net income multiples) observed in these transactions are applied to derive a valuation range.
This approach has the advantage of anchoring the valuation in market reality. It answers the question: how much are buyers actually paying for this type of business?
Limitations caused by a lack of comparable transactions
For microbusinesses and SMEs, transaction databases remain incomplete. The lack of reliable comparables limits the usefulness of this method and makes it necessary to document the assumptions used in detail, as the FRC’s recommendations on valuation transparency emphasize. A niche business with no direct competitor recently sold can only rely on the comparable company approach to a limited extent.
Industry benchmarks published by some organizations provide a rough guide, but they smooth over differences between businesses in the same sector. A well-located restaurant and a struggling one in the same city fall under the same benchmark, even though their actual valuations are nothing alike.
Family succession and tax considerations: the Dutreil pact
Valuation is not used solely to set a sale price. In a family succession, the value selected directly determines the tax base for transfer duties. Subject to certain conditions, the Dutreil pact provides for a partial exemption on the value transferred when calculating transfer duties. The classification of the business (operating or asset-holding) and the valuation method chosen therefore affect the tax cost of the transfer.
This context calls for a combination of methods: asset-based valuation for assets, earnings-based valuation for cash flows and comparable company valuation for the market. Relying on a single approach exposes the taxpayer to a reassessment if the tax authorities consider the declared value to be understated.
- Document every calculation assumption and the source of the data used
- Review the valuation at each reporting date, taking current market conditions into account
- Keep the comparable data used to support the selected multiples
A well-prepared valuation does not guarantee that it will go unchallenged, but it provides a solid basis for discussion with a buyer or the tax authorities. Using at least two methods remains the most defensible practice, whatever the circumstances of the transaction.


